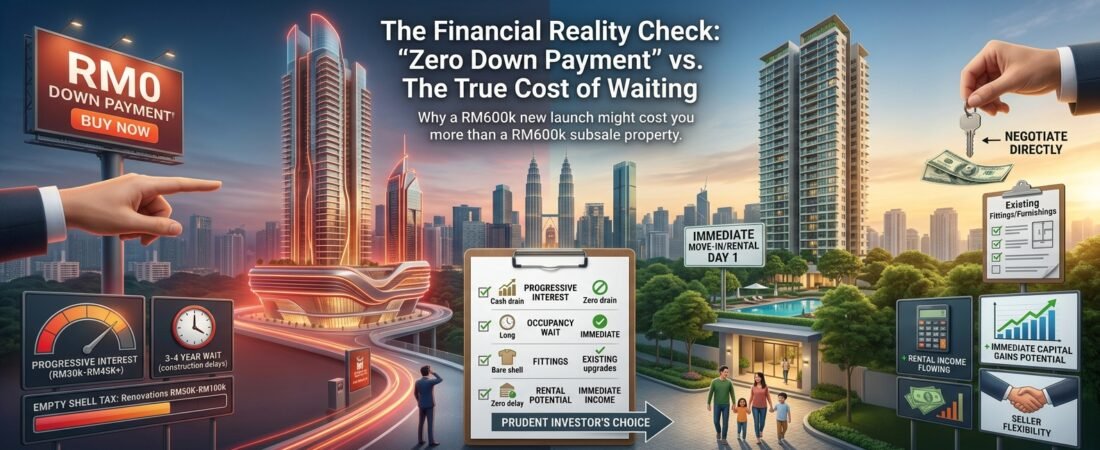
Is Buying New Project Really Cheap?
Two weeks ago, we examined why the Klang Valley secondary market offers unmatched spatial value and location certainty. Following that post, the most common question I received from clients was:
“What about the upfront cash? New launches offer zero down payment, legal fee absorptions, and attractive rebates—isn’t that cheaper?”
It is easy to see why marketing slogans like “Zero Down Payment” and “RM1,000 Booking Fee” draw attention. However, prudent capital management requires looking beyond the initial sign-up incentives to calculate the true total cost of ownership over a 3- to 4-year period.
When you do the math, a RM600,000 new launch often carries a significantly higher net financial strain than a RM600,000 completed subsale property.
Here is why.
1. Progressive Interest: The Silent Capital Drain
When buying an uncompleted primary development, you don’t pay your full mortgage immediately—instead, you pay progressive interest as construction milestones are completed.
-
The Reality: Over a standard 36 to 48-month build cycle, progressive interest payments steadily scale up. On a RM600,000 property, you can easily pay RM25,000 to RM45,000+ in cumulative interest to the bank before ever receiving the keys.
-
The Opportunity Cost: That money is 100% unrecoverable holding friction. During those 3 to 4 years, the unit generates zero rental yield and provides zero personal utility.
Conversely, with a subsale property, your mortgage payments begin immediately alongside full asset utility—meaning you can occupy the home or collect rental income on Day 1 to offset your financing costs.
2. The “Empty Shell” Tax
Showroom units in sales galleries are masterfully staged with thousands of Ringgit in custom interior design, mirrors, and strategic lighting. But what you actually receive at Vacant Possession (VP) is often a bare brick-and-concrete shell.
To make a brand-new bare unit livable or tenant-ready, you must cover:
- Built-in kitchen cabinets and appliances
- Air conditioning units and water heaters
- Plaster ceilings, lighting, and grilles
- Window coverings and custom wardrobes
In today’s market, fitting out a bare 800 sq. ft. unit costs an additional RM50,000 to RM100,000 out of pocket. That is capital you must deploy after taking possession, effectively pushing your real entry cost to RM650,000+.
3. The Subsale Counter-Strategy: Negotiability & Existing Upgrades
The secondary market operates on human negotiations, not rigid developer price lists. This creates two distinct capital advantages:
-
Move-in Ready Renovations: Many subsale sellers have already absorbed the “Empty Shell” tax. Buying a well-maintained, partially or fully furnished unit saves you tens of thousands in immediate capital expenditure.
-
Price & Term Flexibility: In a balanced secondary market, sellers have different motivations. A strategic buyer can negotiate hard on the purchase price, request structural repairs, or negotiate flexible settlement timelines.
The True Cost Comparison: RM600k New Launch vs. RM600k Subsale
| Expense Category | RM600k New Launch (Primary) | RM600k Completed Subsale (Secondary) |
| Upfront Down Payment | RM0 – Low (Covered by rebates) | ~10% (Negotiable / Valuation dependent) |
| 3–4 Year Construction Interest | ~RM30,000 – RM45,000 (Pure outflow) | RM0 (Immediate move-in or rental yield) |
| Fitting Out & Renovation | ~RM50,000 – RM100,000 (Bare shell) | RM0 – RM20,000 (Often partially/fully fitted) |
| Rental Revenue during Years 1–4 | RM0 | ~RM21,600 – RM32,400 * ( ~3.6%-5.4% yield) |
| Asset Risk | Construction delays, defective work | Physically inspected, proven CCC status |
* This baseline estimate corresponds to an annual gross rental yield of 3.6% to 5.4%, matching current Malaysian market standards. The actual rental price depends heavily on the property type, location, and furnishing status.
The Bottom Line
A “Zero Down Payment” rebate is simply a financial structuring tool—it does not change the physical costs of construction waiting periods, progressive interest, or post-key-collection fit-outs.
When evaluating properties in the Klang Valley, don’t let sales gallery packaging obscure the long-term holding balance sheet.
Ask yourself: Would you rather pay for a developer’s future promise, or negotiate a tangible, income-generating hard asset today?